Renters Insurance 2026: What It Covers, What It Costs
Renters insurance costs about $13 a month in 2026, and it covers the belongings, liability, and hotel stay your landlord's policy never touches. Here is what it covers, what it leaves out, what it costs in your state, and how to buy it in one afternoon.
The short answer: renters insurance costs about $13 to $15 a month in 2026 for a standard policy, and it covers your belongings, your liability to other people, and a hotel stay if a covered disaster makes your place unlivable. Your landlord's building policy covers none of those, and flood and earthquake damage need separate coverage.
Key numbers at a glance
- $13 to $15 typical monthly cost of a standard 2026 policy, $151 a year in NerdWallet's sample, $182 a year in MoneyGeek's sample
- $30,000 personal property and $100,000 liability in the standard NerdWallet sample, rising to $295 a year with poor credit
- $300,000 liability limit worth buying for most renters, usually only a few dollars a month more than $100,000
- 30 days waiting period on separate NFIP flood contents coverage, up to $100,000
- 10 to 25% typical saving from bundling renters and auto insurance
- 310 dollars a year is what MoneyGeek's 2026 analysis puts at 50,000 dollars of property coverage, against 182 dollars a year for 20,000 dollars of property and 100,000 dollars of liability
- 650 dollars against 1,100 dollars is the actual-cash-value versus replacement-cost gap on a three-year-old laptop, for usually only a few dollars a month more
Priya moved into a second floor walkup in Austin last spring with a laptop, a bike, a mattress on the floor, and about $9,000 worth of stuff she had bought piece by piece over five years. She skipped renters insurance because the building looked solid and the landlord never asked for it. In July a washing machine hose burst in the unit above hers. Water came through her ceiling for hours while she was at work. Her laptop survived on a desk by luck. Her mattress, her clothes, her bike, and a stack of books did not. The upstairs neighbor had no insurance either, and the landlord's policy paid for the ceiling and the floor, not one thing Priya owned. She paid $4,100 out of pocket to start over, and she told me later that the worst part was not the money. It was learning, after the fact, that a policy costing about the price of two coffees a month would have covered almost all of it.
That gap is the whole story of renters insurance. Most renters think it is optional because no law requires it, and most landlords think their building policy covers tenants, which it does not. The result is that millions of people with $20,000 to $40,000 of belongings in a rented home carry zero protection for them, while a policy that costs roughly $13 to $15 a month sits unpurchased. This guide fixes that gap with real 2026 numbers: what a standard policy covers, what it leaves out, what it costs in your state, what your lease can actually require, and the exact steps to buy a good policy in one afternoon.
Renters insurance coverage: what it actually covers
Renters insurance is a policy, usually an HO-4 form, that covers your belongings, your liability to other people, and a hotel stay if a covered disaster makes your place unlivable.
A standard renters policy, usually an HO-4 form, has four parts, and they work together in ways most renters never hear about until they need one of them. Personal property coverage pays to repair or replace your belongings after a covered event like fire, theft, vandalism, a burst pipe, or wind damage. Personal liability coverage pays if you accidentally injure someone or damage their property, for example if your dog bites a guest or your bathtub overflows into the unit below. Medical payments coverage pays small medical bills for guests hurt in your home, no lawsuit needed. Additional living expenses, often called loss of use, pays for a hotel and extra food costs if a covered event makes your place unlivable.
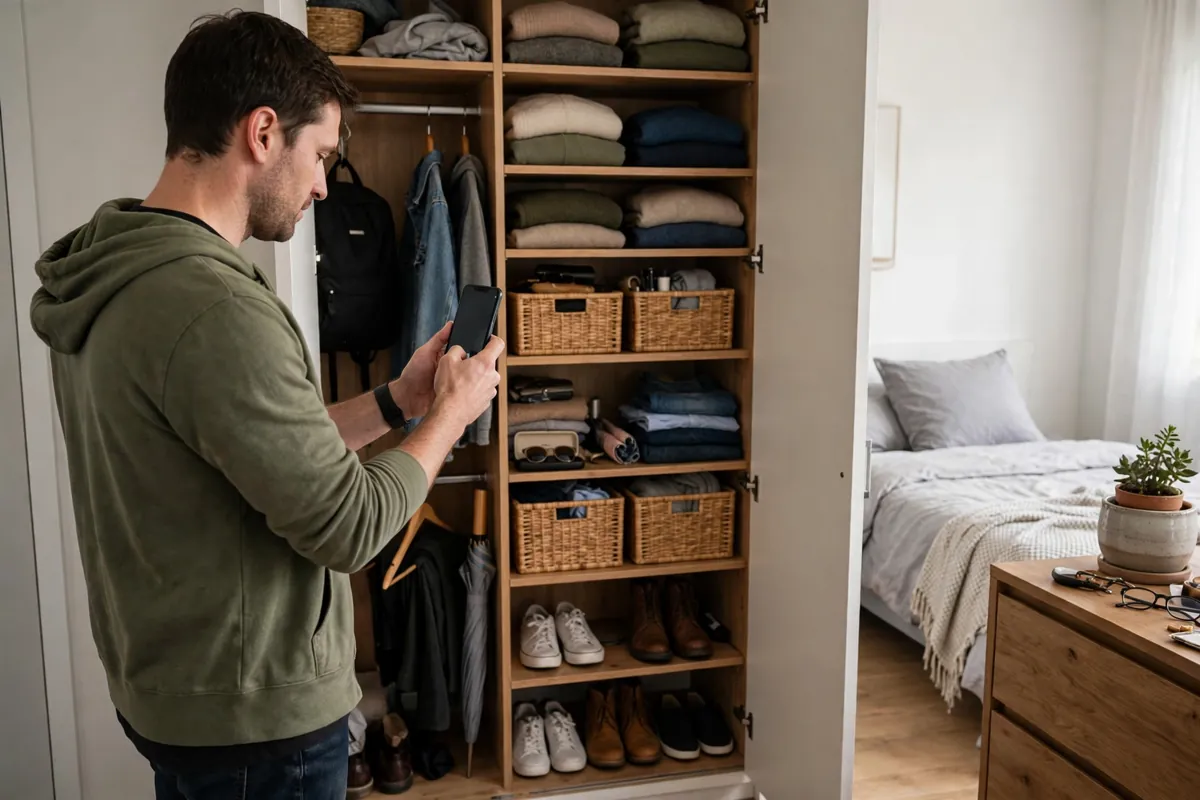
The part that surprises people most is that personal property coverage travels with you. A laptop stolen from your car, a bag taken while you travel, a bike stolen from a rack outside work: many policies cover those under the same personal property limit, sometimes at a lower cap for items away from home. Read that clause before you assume it, because the away from home cap is often 10 percent of your total limit, which still beats nothing. Another surprise is how fast belongings add up. Walk your place with a phone camera, open every closet and drawer, and add up replacement prices. Most renters who do this land between $20,000 and $40,000, even in a small apartment, because a laptop, a phone, a television, clothes, kitchen gear, and furniture stack up faster than anyone expects. MoneyGeek's 2026 analysis puts the national average at $15 a month, $182 a year, for $20,000 of personal property and $100,000 of liability, and notes that renters who pick $50,000 of property coverage pay about $310 a year. The room by room video you shoot today is also your claims evidence later, so store it in the cloud, not only on the phone that could be the thing stolen.
One choice inside this section matters more than any other: replacement cost versus actual cash value. Actual cash value pays what your used things were worth, after depreciation, so a three year old laptop might bring $650. Replacement cost pays what a new one costs, closer to $1,100 in that same example, and it usually adds only a few dollars a month. For most renters this is the single upgrade worth buying. If your policy quote defaults to actual cash value, ask for the replacement cost version and compare the two prices side by side before you decide.
What renters insurance does not cover
The exclusions are where renters get hurt, because they assume a policy covers everything bad that can happen to a home. It does not. Flood is the biggest gap. A standard renters policy excludes flood damage, including storm surge, and that exclusion holds even if the water comes from a hurricane. Contents only flood coverage is available separately through the National Flood Insurance Program, up to $100,000, with a 30 day waiting period, so it cannot be bought the week a storm is forecast. Earthquake damage is also excluded unless you add an endorsement, and in California the state earthquake authority sells separate renters policies. The building itself is excluded too, but that is the landlord's job, not yours, and a policy that tried to cover the structure would cost far more.
Other exclusions are smaller but still catch people. Wear and tear, pests, and most mold are not covered. A slow leak you ignored for months is a maintenance problem, not a sudden event, and insurers treat it that way. High value items sit under sublimits unless you schedule them: jewelry, watches, art, collectibles, and firearms often cap at $1,000 to $2,500 per category on a standard policy. If your engagement ring alone is worth $6,000, a standard policy will not make you whole, and you need a scheduled personal property rider with an appraisal. Business property in a rented home is capped too, usually around $2,500 on premises, which matters for founders who keep inventory or expensive gear at home. Roommates are another trap. A policy names the people it covers, and an unnamed roommate's belongings are generally not covered, so two roommates need either a joint policy that names both or two separate policies.
The honest way to read exclusions is as a shopping list for riders, not a reason to skip insurance. Flood risk, earthquake risk, a valuable ring, a home business: each has a specific add on with a specific price. What you cannot do is buy the add on after the loss, so the time to check your flood zone and your jewelry drawer is the same afternoon you buy the base policy.
Renters insurance cost 2026: state prices and discounts
Renters insurance is the cheapest major insurance most Americans can buy, and the 2026 numbers prove it. NerdWallet's 2026 sample puts the national average at $151 a year, about $13 a month, for $30,000 of personal property and $100,000 of liability with good credit, rising to about $295 a year with poor credit. MoneyGeek's sample, using $20,000 of property, averages $182 a year. The difference between the two is mostly the coverage amount, which is exactly the point: your price follows your choices, not a fixed national rate. The cheapest states run $8 to $10 a month, Alaska, Vermont, Maine, and Wyoming among them, while Louisiana and Mississippi run closer to $19 to $22 a month in some samples, and city level prices can spike far higher, with Detroit averaging near $79 a month in one city ranking because of theft and property risk. Your zip code, your building's age and construction, your claims history, and your credit based insurance score in most states all move the number.
| Coverage level | Typical monthly cost | Who it fits |
|---|---|---|
| $20,000 property, $100,000 liability | $13 to $15 | Single renter, modest furnishings |
| $30,000 property, $300,000 liability, replacement cost | $16 to $24 | Most singles and couples |
| $50,000 property, $500,000 liability, plus riders | $28 to $45 | Families, home offices, high value gear |
Three levers cut the price without gutting the coverage. Bundling with an auto policy is the biggest, often 10 to 25 percent off, and some insurers discount further for a monitored alarm, a sprinkler system, or a newer building. Raising the deductible from $500 to $1,000 saves roughly $14 a year in MoneyGeek's data, which is small, so only raise it if you can actually pay $1,000 the same week a loss happens. Paying annually instead of monthly avoids installment fees, usually $3 to $8 per payment. The lever that hurts is the one people reach for first: cutting the property limit in half to save $4 a month, then discovering after a fire that the limit covers only half their belongings. Price the policy you actually need, then use bundling and discounts to bring that price down, not the other way around.
Credit deserves its own warning. In most states insurers use a credit based insurance score, and MoneyGeek's data shows renters with poor credit paying about $480 a year against $153 for excellent credit on the same coverage. That gap is larger than the whole policy for many people, and it is one more reason to check your credit report before you shop, dispute errors early, and get quotes from at least three insurers, because each one weights credit differently. A renter with a thin file can also see a wide spread between quotes, which is why identical limits on every quote matter: compare the same property limit, liability limit, deductible, and replacement cost setting, or the comparison is meaningless.
Why is liability the part renters forget?
Ask renters what their policy is for and almost everyone says their stuff. Ask claims adjusters and they will tell you liability is the coverage that saves people from real financial damage. Personal liability on a renters policy typically starts at $100,000, and many landlords now require $300,000. It pays for bodily injury or property damage you cause by accident, plus your legal defense if someone sues. The classic examples are unglamorous and common: a guest trips on a rug and breaks a wrist, your dog nips a neighbor's child at the dog park, your washing machine hose fails and ruins the ceiling and furniture of the unit below, a candle tips over and scorches a neighbor's wall. None of these require you to be careless in any dramatic sense. They require one bad afternoon.
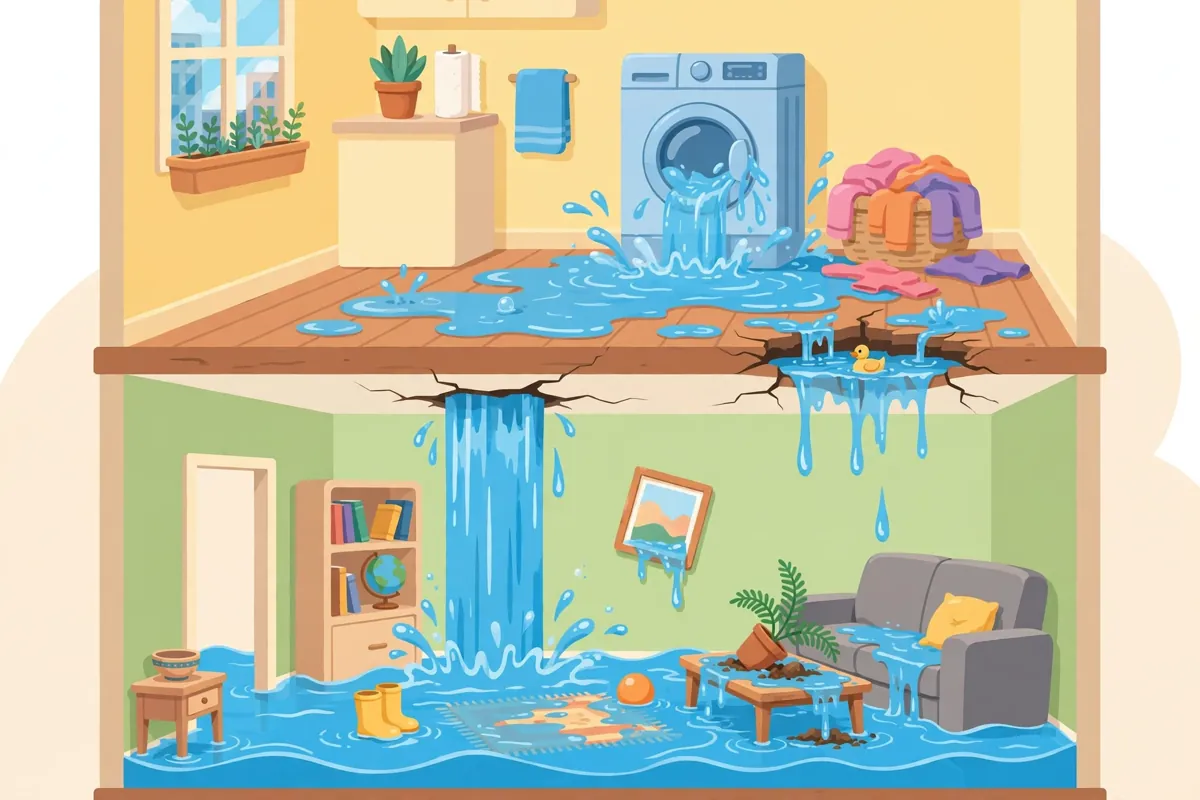
Priya's story is a liability story in reverse. The upstairs neighbor's failed hose damaged her belongings, and because that neighbor had no liability coverage, there was no insurer to pay Priya. Had the roles been reversed, Priya's own liability coverage would have paid her neighbor's loss and her legal costs. That is the part renters miss when they compare policies by property limit alone. A $100,000 liability limit sounds generous until a serious injury involves surgery and months off work, at which point medical bills and lost wages can pass it quickly. The jump from $100,000 to $300,000 of liability usually costs only a few dollars a month, and for renters with a dog, a trampoline on a rented lot, or frequent guests, it is the cheapest peace of mind in the policy. If you own a dog breed your insurer restricts, check the breed list before you buy, because some insurers exclude certain breeds from liability coverage entirely, and finding out after a bite is the worst time to learn it.
Medical payments coverage sits beside liability and works differently: it pays small guest medical bills, often $1,000 to $5,000, without anyone having to prove fault or file a lawsuit. It exists so a guest's emergency room visit after a fall in your kitchen does not have to become a legal fight. Use it generously when it applies. A quick, no fault payment keeps a neighbor a neighbor, and it often stops a small injury from growing into a claim.
What do landlords require, and what does the lease fine print say?
No state requires renters insurance by law, but your lease can require it, and that requirement is enforceable in most states. Landlords commonly ask for $100,000 of liability coverage and ask to be listed as an interested party or additional interested party, which means the insurer tells them if your policy lapses or is cancelled. Some leases go further and require proof of coverage before you get the keys, or require you to maintain coverage for the full lease term. Letting a required policy lapse can put you in breach of lease, and a landlord can treat a breach as grounds for penalties or, in a strict lease, eviction proceedings. Read the insurance clause before you sign, not after you move in, and note whether it sets a minimum liability limit, a minimum property limit, or a requirement to name the landlord.
Two lease details deserve a closer look. First, the interested party clause is not the landlord insuring your belongings, and it does not give the landlord a claim on your payout. It is a notification arrangement. Your property payout is still yours. Second, some leases contain a waiver of subrogation or a clause that each side's insurer waives claims against the other, which can affect who pays after a building level loss. If your lease has one, ask your insurer whether it changes your coverage before you sign. Also check the lease for who pays the deductible on building damage you cause, and whether the landlord can require you to carry coverage for a pet, a waterbed, or a home business. None of these clauses are reasons to avoid a lease, but all of them are reasons to match your policy to the lease instead of buying the cheapest quote and hoping the paperwork lines up.
If your landlord does not require insurance, buy it anyway. The landlord's building policy covers the walls, the roof, and the common areas. It does not cover your couch, your laptop, your liability to a guest, or your hotel bill after a fire. That division is not a loophole. It is how property insurance has always worked, and renters who learn it from a claims denial learn it too late.
How to buy a good policy in one afternoon
Buying renters insurance well takes about two hours, and most of that is the inventory, not the shopping. Start with the video walkthrough of your place, room by room, with closets and drawers open, and total the replacement cost of what you see. Add high value items separately with photos and receipts or appraisals, and flag anything over the standard sublimit for a rider. Then decide your numbers before you talk to any insurer: property limit from your inventory, $300,000 liability unless your lease or your risk says otherwise, replacement cost, and a deductible you can pay this week, usually $500. Writing those numbers down first stops a sales conversation from quietly shrinking them.
Get three quotes with identical limits, deductibles, and replacement cost settings. Include one national insurer, one digital first insurer like Lemonade, which advertises plans starting around $5 to $8 a month at lower limits, and one independent agent who can compare several carriers at once. Ask each one the same five questions: is this replacement cost or actual cash value, what are the sublimits for jewelry and electronics, does the policy cover belongings away from home and at what cap, is my dog breed covered for liability, and what discounts apply for bundling, alarms, or paying annually. The answers will differ more than the prices do, and the differences are where claims get won or lost. J.D. Power's 2026 renters study ranked State Farm, Erie, and Amica highest for customer satisfaction, which is useful context, but satisfaction scores do not replace reading your own policy's exclusions.
When you pick a policy, check the declarations page line by line before you pay: names of all insured people, property limit, liability limit, medical payments limit, deductible, replacement cost wording, and any endorsements you bought. Set the policy to start the day you move in or the day your old policy ends, with no gap, and send the landlord proof only if the lease requires it, with the interested party clause added if asked. Put a calendar reminder for renewal and for any move, because a policy tied to one address does not automatically follow you to the next apartment, and a gap during a move is exactly when belongings sit in a truck or a hallway.
How to file a claim without a fight
Claims go badly for two reasons: slow reporting and thin proof. Fix both and most claims go smoothly. After a covered loss, first make the place safe and stop further damage if you can do so without risk, for example shutting off water or moving undamaged items. Take photos and video before you clean up, and keep damaged items until the adjuster says otherwise. Call your insurer promptly, many policies require prompt notice, and get a claim number and the adjuster's name in writing. Then file a police report for theft or vandalism, because insurers ask for it and a report filed weeks later reads differently from one filed the same day.
Your inventory video is now your best asset. Send it with a list of damaged or stolen items, each with an approximate purchase date and replacement price, and keep receipts for anything you replace, plus receipts for hotel and food costs under additional living expenses. Insurers pay additional living expenses only for the extra cost over your normal spending, so keep grocery and restaurant receipts and note your normal weekly food budget. Do not throw away receipts, do not agree to a recorded statement without reading your policy's duties section, and do not accept a first offer if it uses actual cash value on a replacement cost policy. A polite, documented challenge with your inventory and replacement prices resolves most underpayments without a lawyer. If a claim is denied, ask for the denial in writing with the exact policy section cited, and check whether your state insurance department offers a consumer complaint process, which costs nothing and often gets a second review.
One last claims habit matters for founders and remote workers in particular: document business gear separately. A laptop used for work, a camera, inventory stored at home, and a home office setup can blur the line between personal and business property, and a standard renters policy caps business property low. A home business endorsement or a separate small business policy closes that gap, and it costs far less than replacing a work setup out of pocket after a fire. Tell your insurer about the home business before a loss, not during the claim call.
The bottom line
Renters insurance in 2026 costs about $13 to $15 a month for a standard policy, and it covers the three things a landlord's policy never will: your belongings, your liability to other people, and a place to stay after a covered disaster. The expensive mistakes are all avoidable: buying actual cash value when replacement cost costs a few dollars more, skipping flood coverage in a flood zone, letting a roommate stay unnamed on the policy, and choosing a property limit from a guess instead of a ten minute video inventory.
Do the inventory this week, get three identical quotes, and pick the policy that matches your lease and your real belongings. It is the cheapest policy most renters will ever buy, and the one most likely to matter on the worst day of a tenancy.
Start with the inventory, not the quote: most renters land between 20,000 and 40,000 dollars of belongings even in a small apartment, so count the laptop, phone, television, and furniture before choosing a limit, because a policy bought on a guessed number is the one that pays a guessed amount.
Frequently asked questions
How much does renters insurance cost in 2026?
About $13 to $15 a month for a standard policy, or $151 to $182 a year in the two major 2026 samples, for $30,000 or $20,000 of personal property and $100,000 of liability. Your state, building, credit based insurance score, and coverage choices move the price, and bundling with auto insurance often cuts 10 to 25 percent.
Can my landlord require renters insurance?
Yes, if the lease says so. No state requires it by law, but landlords commonly require $100,000 of liability coverage and ask to be listed as an interested party so they are told if your policy lapses. Letting a required policy lapse can put you in breach of your lease.
Does renters insurance cover flood damage?
No. Standard renters policies exclude flood, including storm surge. Contents only flood coverage up to $100,000 is available separately through the National Flood Insurance Program, with a 30 day waiting period, so it must be bought well before a storm.
Does it cover my roommate's belongings?
Only if your roommate is named on the policy. An unnamed roommate's belongings are generally not covered, so roommates need a joint policy naming both people or two separate policies.
Should I choose replacement cost or actual cash value?
Replacement cost for most renters. Actual cash value pays what used items were worth after depreciation, while replacement cost pays what new items cost, and the upgrade usually adds only a few dollars a month.
For the wider insurance picture, read our disability insurance guide for self-employed founders for the income protection renters policies do not provide, our term life insurance guide for the coverage that protects the people who depend on you, and our emergency fund guide for the cash buffer that covers your deductible. For outside data, see MoneyGeek's average cost of renters insurance in 2026, InsuredBetter's renters insurance cost by state and city, and BeSecuredNow's renters insurance guide.
Want more practical guides like this?
Browse all 88 guides across 10 categories, no fluff, no paywall.
Browse all guides →Explore Insurance guides